STX Lending, Texas Mortgage Lender
  • Rates
(210) 750-6164Get Started
STX Lending

Texas Real Estate Lending, Simplified. We provide fast, transparent mortgage lending with competitive rates and a streamlined digital experience.

1846 N Loop 1604 W, Ste 205

San Antonio, TX 78248

(210) 750-6164hello@stxlending.com

Hours

Monday to Saturday: 7:00 AM to 8:00 PM

Sunday: Closed

Proudly serving Texas since 2019.

Find us on Google Business Profile.

Solutions

  • Home Purchase
  • Refinance Rates
  • Texas Cash-Out
  • VA Loans
  • Get Pre-Approved
  • Texas Loan Limits

Resources

  • Daily Rates
  • Calculators
  • HELOC Calculator
  • Loan Comparison
  • Mortgage Blog
  • STX Perks
  • Careers
  • About Us

Texas Locations

  • All Texas locations
  • San Antonio
  • Austin
  • Houston
  • Dallas
  • Fort Worth
  • Corpus Christi

Legal & Support

  • Contact Us
  • Privacy Policy
  • Terms of Service
  • State Licenses & NMLS
  • Accessibility
  • Data Opt-Out

Awards & Recognition

  • National Mortgage News Top Producers 2025
  • 5 Star Award, Top Producer
  • Five Star Professional, Rising Star
  • Top Mortgage Professionals, 2025

Memberships

  • National Association of Hispanic Real Estate Professionals (NAHREP)
  • Five Star Professional
  • Top Mortgage Professionals 2025
  • Romanian American Business Owners of America

South Texas Lending Team is a mortgage team of Neighborhood Loans, Inc. (NMLS #222982). All loans are made by Neighborhood Loans, Inc. Verify on NMLS Consumer Access.

San Antonio, TX Branch · NMLS #2774284 · 1846 N Loop 1604 W, Ste 205, San Antonio, TX 78248

Branch Manager: Benjamin Gheliuc · Mortgage Loan Originator · NMLS #1775990 · Branch line: (630) 246-4777

Corporate Headquarters: Neighborhood Loans, Inc., 1333 Butterfield Rd, Suite 600, Downers Grove, IL 60515. For complaints or questions about this branch, contact the Texas Department of Savings and Mortgage Lending, 2601 N. Lamar Blvd, Suite 201, Austin, TX 78705, 1-877-276-5550.

© 2026 Neighborhood Loans, Inc. All rights reserved.

NMLS #222982NMLS Consumer Access
Equal Housing Lender
Talk to Ben(210) 750-6164
No SSN • 60 SecSee Options
Home>Purchase>Physician Loans
Physician Mortgage Program

Built specifically for doctors. 0% down. No PMI.

Texas physician mortgage loans designed for MDs, DOs, dentists, and other medical professionals. Flexible student loan treatment, ability to qualify with an employment contract, and loan amounts going up to $2M+.
Check my eligibility Call (210) 750-6164
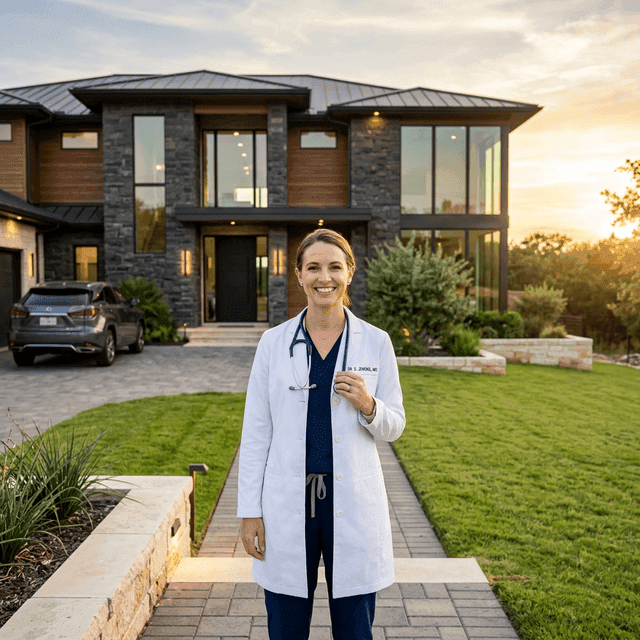
Doctor standing in front of luxury Texas home
Physician Loan
0% down • No PMI
0%
Down payment
No PMI
Ever.
$2M+
Max loan amount

Who qualifies for a physician mortgage?

These programs are built around specific medical degrees that allow for 0% down and PMI financing.

Medical Doctors (MD/DO)

This is for licensed physicians including attendings, residents, and fellows. If you haven't started yet, you can still qualify using your signed employment contract.

Dentists (DMD/DDS)

Both general dentists and specialists qualify - orthodontists, oral surgeons, periodontists, endodontists, and more.

Residents & Fellows

Still in training? You can qualify with a signed contract or residency match letter. In many cases, we can use your future attending income - not your current resident pay.

Optometrists (OD)

Licensed optometrists can qualify under certain physician loan programs. We'll confirm eligibility based on the specific program.

Podiatrists (DPM)

Doctors of Podiatric Medicine are eligible under many physician mortgage options available here in Texas.

Other Medical Pros

Some programs also extend to PharmDs, CRNAs, PAs, NPs, and similar roles. Eligibility depends on the lender - ask us about expanded options.

Why physicians choose this loan

This loan for Physician Mortgages is built around the real challenges medical professionals face - large student debt, delayed income while in training, and needing to buy a home before starting a new position. Estimate your numbers with our mortgage calculator.

0% down - up to $1M+

Most programs allow you to purchase with 0% down up to $1M, and with 5-10% down options extending to $2M+. No matter the down payment - there's no PMI.

No PMI - Ever

Unlike conventional loans where you pay PMI until you 20% equity, physician loans don't charge PMI at all. That alone can save you anywhere from $300 to $800+ per month depending on your loan size.

Student loan flexibility

This is a big one because loans in deferment or on income based repayment (IBR) may be excluded completely - or calculated at just 0.5% of the balance instead of the standard 1%.

Employment contract qualifying

You don't have to wait until your first paycheck! We can use your signed employment contract as proof of income, which is ideal if you are relocating or transitioning from residency to an attending role.
See if I qualify
Luxury home interior suited for a medical professional in texas

Physician mortgage vs. conventional

Here's why physician loans are structured differently - and why they often make more sense for your situation.

Feature
Physician Loan
Conventional
Jumbo
Down payment
0% up to $1M+
3–20%
10–20%
PMI
None — ever
Yes (until 20% equity)
Typically none
Student loan DTI
Excluded or 0.5%
0.5–1% of balance
1% of balance
Employment contract OK
Yes
No (need pay stubs)
No
Max loan amount
$1M–$2M+
$832,750
$2M–$3M+
Credit score minimum
680–700
620
700+
Residency income
Future attending salary
Current pay only
Current pay only
Property types
Primary residence only
Primary, second, investment
Closing timeline
14–21 days
14–30 days
21–45 days
Best for
MDs, DOs, DMDs with student debt
Established earners, 20%+ equity
High-net-worth buyers

Physician mortgage in 4 steps

Streamlined for busy medical professionals.

01

Verify your eligibility

We confirm your degree, license, and employment details. Whether you are currently working or starting soon, we can usually pre-qualify you with a quick call.

02

Get pre-approved

We run your numbers using physician loan guidelines - including student loan flexibility - so you get a real picture of your buying power, not a limited one.

03

Find your Texas home

Shop confidently knowing your approval is based on 0% down and no PMI. Your pre-approval letter shows sellers you are a strong and serious buyer.

04

Close in 14–21 days

The team we have in-house moves quicker than national banks. We can even close before your official start date if needed or we can close on your schedule.

Physician Mortgage FAQ

Common questions from doctors and dentists buying homes in Texas.

MDs, DOs, DMDs, and DDSs are widely accepted across all programs. Some lenders also include PharmDs, ODs, DPMs, CRNAs, NPs, and PAs. Most programs are designed for professionals within their first 10 years of practice, including residents and fellows. If you haven't started yet, your signed contract can be used instead of pay stubs.
Typically, with a physician mortgage, up to $1M with 0% down and no PMI. The program extends to $1.5M with 5% down. Your exact limit will depend on your credit score, income, and debt-to-income ratio.
There are three main differences: (1) No PMI at any loan-to-value -- conventional loans require it under 20% equity. (2) Flexibility for student loans - conventional loans are stricter with calculations. (3) Qualify with employment contract - your current paystubs are required for conventional loans. The tradeoff is that rates can sometimes be a little higher than the lowest conventional rates.
Most definitely - these physician mortgages loans are created directly for residents and fellows. You can qualify using your contract or match letter, and in some cases, we can use your future attending income instead of your current stipend.
This is where these loans really stand out. Typically, conventional loans count student loans at 0.5%-1% of the total balance for debt-to-income purposes - even if they are deferred. While the physician loan may exclude student loans entirely or use your income-based-repayment (IBR). On something like a $300K in student loans, that difference can be what makes or breaks your approval.
Most physician mortgages are focused on purchases, but some programs do allow refinancing. And if you already own a home, we can also look at conventional refinance options to see what makes the most sense for you.
There are some physician programs that accept 680, but most programs look for at least a 700 credit score. If you are at 740+, you will usually qualify for the best rates. If you are not there yet, we can help map out a plan to get there.
No - these loans are strictly for primary residences. If you are looking at an investment property or second home, we can go over other options like conventional, jumbo or DSCR loans.

Ready to use your medical degree?

Free physician loan consultation

Check eligibility online

Talk to a physician loan specialist

(210) 750-6164

Your medical degree, your Texas home

0% down. No PMI. Built for doctors.

Check my eligibility