STX Lending, Texas Mortgage Lender
  • Rates
(210) 750-6164Get started
STX Lending

Texas Real Estate Lending, Simplified. We provide fast, transparent mortgage lending with competitive rates and a streamlined digital experience.

1846 N Loop 1604 W, Ste 205

San Antonio, TX 78248

(210) 750-6164hello@stxlending.com

Hours

Monday to Saturday: 7:00 AM to 8:00 PM

Sunday: Closed

Proudly serving Texas since 2019.

Find us on Google Business Profile.

Solutions

  • Home Purchase
  • Refinance Rates
  • Texas Cash-Out
  • VA Loans
  • Get Pre-Approved
  • Texas Loan Limits

Resources

  • Daily Rates
  • Calculators
  • HELOC Calculator
  • Loan Comparison
  • Mortgage Blog
  • STX Perks
  • Careers
  • About Us

Texas Locations

  • All Texas locations
  • San Antonio
  • Austin
  • Houston
  • Dallas
  • Fort Worth
  • Corpus Christi

Legal & Support

  • Contact Us
  • Privacy Policy
  • Terms of Service
  • State Licenses & NMLS
  • Accessibility
  • Data Opt-Out

Awards & Recognition

  • National Mortgage News Top Producers 2025
  • 5 Star Award, Top Producer
  • Five Star Professional, Rising Star
  • Top Mortgage Professionals, 2025

Memberships

  • National Association of Hispanic Real Estate Professionals (NAHREP)
  • Five Star Professional
  • Top Mortgage Professionals 2025
  • Romanian American Business Owners of America

South Texas Lending Team is a mortgage team of Neighborhood Loans, Inc. (NMLS #222982). All loans are made by Neighborhood Loans, Inc. Verify on NMLS Consumer Access.

San Antonio, TX Branch · NMLS #2774284 · 1846 N Loop 1604 W, Ste 205, San Antonio, TX 78248

Branch Manager: Benjamin Gheliuc · Mortgage Loan Originator · NMLS #1775990 · Branch line: (630) 246-4777

Corporate Headquarters: Neighborhood Loans, Inc., 1333 Butterfield Rd, Suite 600, Downers Grove, IL 60515. For complaints or questions about this branch, contact the Texas Department of Savings and Mortgage Lending, 2601 N. Lamar Blvd, Suite 201, Austin, TX 78705, 1-877-276-5550.

© 2026 Neighborhood Loans, Inc. All rights reserved.

NMLS #222982NMLS Consumer Access
Equal Housing Lender
Call
Get started
Home/Loans/DSCR Loans/Portfolio & Blanket

DSCR Portfolio Loans in Texas

Finance or refinance 2 to 10 Texas rental properties under one blanket mortgage instead of managing separate loans, title policies, and monthly payments on every house. Qualification runs on the portfolio’s combined rental income rather than personal tax returns or W-2s, and borrowers can close in a standard LLC or a Texas Series LLC.
Get startedCall (210) 750-6164
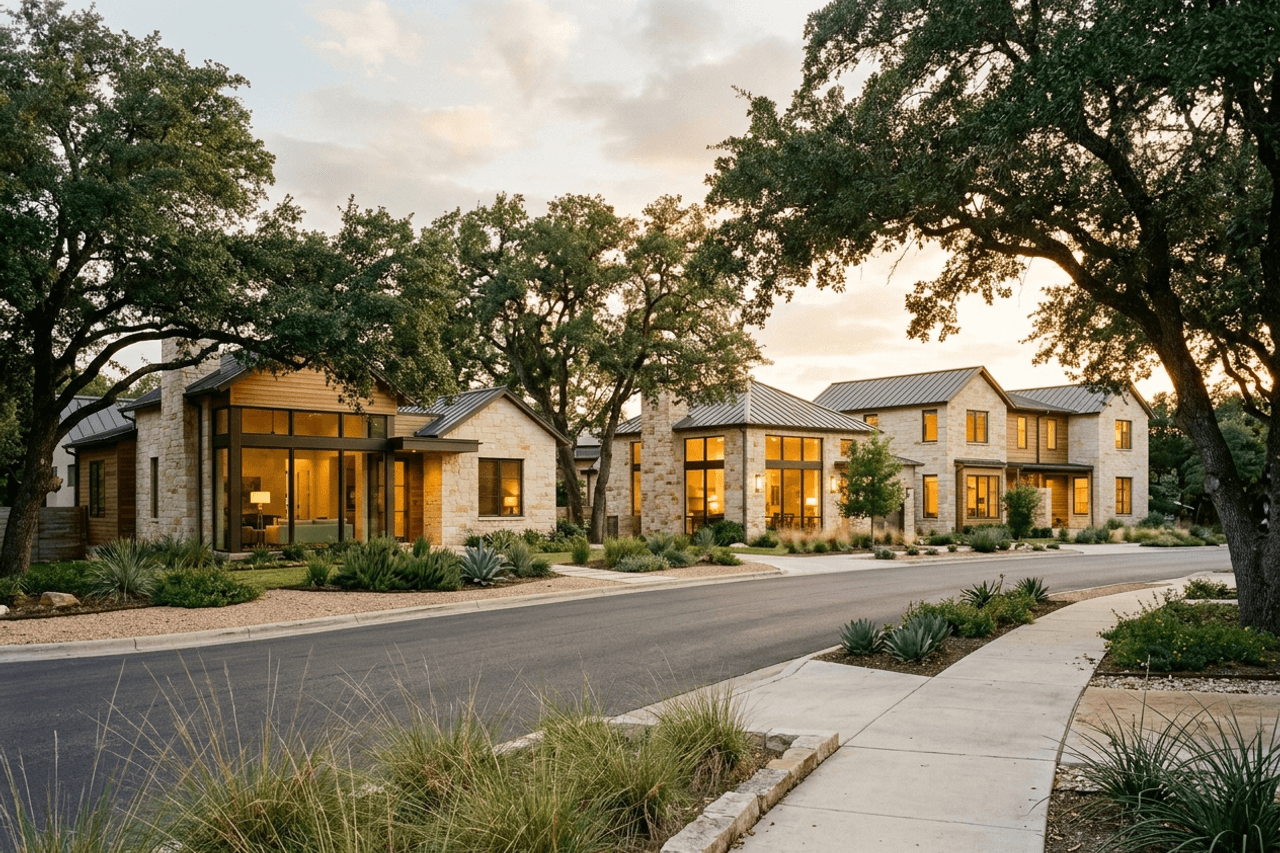
Modern Texas limestone single-family rental homes financed under one DSCR portfolio blanket loan
Properties per loan
2 to 10 Rentals

Up to 15 via linked notes

Maximum loan size
$5,000,000

620 min credit, 0.75+ DSCR

Max leverage
80% Purchase LTV

75% LTV on cash-out refi

Exit flexibility
Partial Release

Sell one house without refinancing

Model your DSCR loan and combined cash flow across 2 to 15 Texas rentals

Estimate proceeds on a DSCR portfolio loan and see the payoff needed to clear a single house if you sell one later. For county property taxes and monthly payment math on one property, use our Texas DSCR calculator.

2 to 10 standard (15 max)
5 Doors
2 doors10 doors (standard cap)15 doors
Avg $300,000 / door
$1,500,000
$300,000$3,500,000$6,500,000
Estimated blanket loan (75% LTV)
$1,125,000
Text Ben
Allocated loan per door (5 doors)$225,000
Payoff to release 1 house (115%)$258,750
Remaining blanket balance (4 doors)$866,250
Get started

No hard credit pull to price your property schedule.

How a blanket loan and cross collateralization work on investment properties

Local bank portfolio mortgage lenders in Texas typically cap packages at 4 or 5 properties inside a single county. A wholesale rental portfolio loan consolidates properties statewide into one cross-collateralized note underwritten on aggregate lease income, avoiding separate origination fees and title policies.
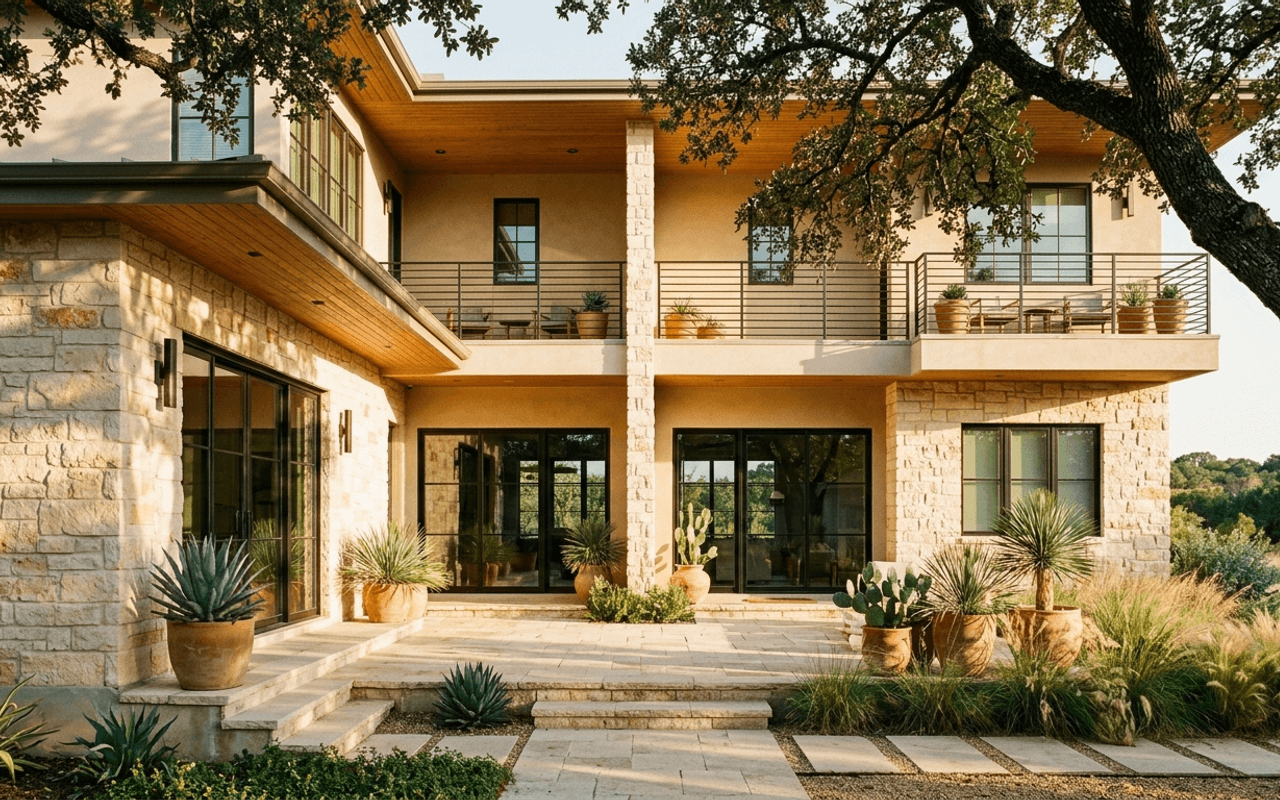
Sunlit Texas limestone duplex rental courtyard representing statewide DSCR portfolio properties across San Antonio, Houston, Austin, and Dallas

Cross collateralization and combined cash flow

One master note holds multiple Texas rentals as collateral, and underwriting divides the combined gross rent roll by a single monthly payment starting at a 0.75 ratio. Stronger cash flow in San Antonio or Houston can offset lower-yielding appreciation properties in Austin or Dallas.

Selling one property out of the loan

When you sell one house out of the pool, a partial release clause lets you pay 115% of that property’s allocated loan balance to clear its lien without refinancing the rest of the note, provided the remaining rentals still meet minimum debt coverage.

Blanket cash out refinance and blanket construction loan takeout in Texas

Seasoned investors pull equity up to 75% LTV across rentals on a DSCR cash out refinance to fund new acquisitions. Builders refinance a completed blanket construction loan into 30-year fixed debt. Under Texas Constitution Article XVI, Section 50(a)(6), the 80% homestead equity cap applies only to a primary home, leaving non-owner-occupied Texas rentals eligible.

Texas Series LLC and lower closing costs

Investors can hold properties in isolated series cells under Texas Business Organizations Code Section 101.601, with each participating series pledged toward the master note. Closing under one borrowing entity means one origination fee and one master title policy instead of separate closings on single-door Texas DSCR loans.

Basic blanket loan vs. individual DSCR loans vs. commercial bank portfolio

Wholesale blanket notes, separate loans per rental property, and commercial bank notes differ on property caps, release terms, recourse, and maturity balloons.

Wholesale BlanketSTX Portfolio
Properties covered2 to 10 (11 to 15 by exception)
Total loan amountUp to $5,000,000
Max purchase LTVUp to 80% (1.25+ DSCR)
Max cash-out LTVUp to 75% across portfolio
Release price clause115% of allocated balance
Income verificationCombined rent rolls (0.75+ DSCR)
Terms30-yr fixed, 40-yr, or 10-yr IO
Get started
FeatureWholesale Blanket DSCR (STX)Individual LoansLocal Bank Basic Blanket Loan
Properties covered2 to 10 (11 to 15 by exception)1 rental property per loan2 to 5+ (local footprint only)
Total loan amountUp to $5,000,000Up to $2,500,000 per doorOften capped at $1M to $2M
Max purchase LTVUp to 80% (1.25+ DSCR)Up to 80% (1.25+ DSCR)70% to 75% typical
Max cash-out LTVUp to 75% across portfolioUp to 75% to 80%65% to 70%
Release clause115% of allocated balanceStandalone lien per houseOften locked or re-underwritten
Income verificationCombined rent rolls (0.75+ DSCR)Single property rent (0.75+ DSCR)2 years of 1040 filings and global DTI
Term and balloon30-yr fixed, 40-yr, or 10-yr IO30-yr fixed, 40-yr, or 10-yr IO5-yr balloon on 20-yr amortization
Entity vestingTexas Series LLC, LLC, LP, CorpLLC, LP, Corp, or personalEntity with full personal recourse
Closing costs and speed1 closing, 1 master title policySeparate origination fees per loan45 to 60+ day committee review

How to buy or refinance multiple properties with one mortgage

Wholesale portfolio underwriting moves from rent roll submission to funding at a Texas title company in 21 days or less when appraisals and entity records are ordered together.

01

Submit your property schedule

You send the investor desk each property address, estimated value, county, and executed lease across primary or secondary Texas rental markets.

02

Loan sizing and property allocation

Underwriting reviews combined lease income, confirms purchase or cash-out proceeds, and sets the loan balance allocated to each address on the schedule.

03

Appraisals and rent schedules

Under Fannie Mae Selling Guide B4-1.2-01, Form 1007 is “Required if the property is a one-unit investment property and the borrower is using rental income to qualify.” Two- to four-unit properties use Form 1025.

04

Single closing, one monthly draft

You sign one master note and blanket deed of trust at closing, receive funds in one wire, and service the portfolio through one monthly payment.
Ben Gheliuc, STX Lending area manager, Texas DSCR portfolio and blanket loans

Benjamin Gheliuc

Area Manager & Licensed Loan Officer · NMLS #1775990

“Once you get past three or four rentals, ordering a separate loan, title policy, and closing package on every house slows you down. Putting the portfolio on one note gives you a single monthly payment while keeping the option to sell off an individual property if your plans change.”

Published & fact-checked by Ben Gheliuc·Nov 17, 2026·Editorial standards
Meet Ben(210) 750-6164Send Rent Roll

DSCR portfolio and blanket mortgage FAQ

Answers to the questions seasoned investors ask about cross-collateralizing several properties, cash-out limits, and partial release clauses.

Yes, a blanket loan covers 2 to 10 Texas rentals on one note, or up to 15 via linked notes. Under Fannie Mae Selling Guide B2-2-03, conventional limits count “the number of one- to four-unit residential properties where the borrower is personally obligated on the mortgage(s)” and stop at 10. Commercial LLC blanket notes carry no agency property ceiling.
Each parcel in the pool is tied to the same debt under cross-collateralization, so a default on one property puts every pledged house at risk, and one title defect or low appraisal can hold up closing. Under CFPB Regulation Z Comment 1026.3(a)-4, “Credit extended to acquire, improve, or maintain rental property (regardless of the number of housing units) that is not owner-occupied is deemed to be for business purposes.” Most commercial blanket notes also carry step-down prepayment penalties during the early years of the term.
Yes. As long as aggregate gross rent across the pool meets the 0.75 minimum ratio, a rent-ready vacant house or lower-yielding rental can stay in the package. For unleased units, the appraiser’s Form 1007 or Form 1025 market rent schedule sets qualifying income, though multiple vacant properties at closing can reduce max LTV by 5% to 10%.
A portfolio purchase allows 20% down, which equals 80% LTV, when combined rental income reaches a 1.25 or higher ratio and the guarantor holds at least a 620 credit score. Pools with a combined ratio between 0.75 and 0.99 require 25% to 30% down and 6 to 12 months of PITIA cash reserves, and higher credit scores qualify for lower interest rates across all tiers.
Non-owner-occupied Texas rentals do not qualify for the $140,000 residence homestead school tax exemption under Texas Tax Code Section 11.13, so full county tax bills and coastal windstorm premiums enter the combined PITIA ratio. Pooling higher-yielding rentals in Bexar, Harris, Tarrant, or Bell County with appreciation properties in Travis, Williamson, or Collin County under one Texas Series LLC blanket mortgage offsets county tax drag above the 0.75 minimum ratio. Estimate county tax bills in our Texas property tax calculator.

Ready to price your Texas rental portfolio?

Send over your property addresses and current rent roll to compare a single blanket note against separate DSCR loans.

Get started(210) 750-6164