STX Lending, Texas Mortgage Lender
  • Rates
(210) 750-6164Get Started
STX Lending

Texas Real Estate Lending, Simplified. We provide fast, transparent mortgage lending with competitive rates and a streamlined digital experience.

1846 N Loop 1604 W, Ste 205

San Antonio, TX 78248

(210) 750-6164hello@stxlending.com

Hours

Monday to Saturday: 7:00 AM to 8:00 PM

Sunday: Closed

Proudly serving Texas since 2019.

Find us on Google Business Profile.

Solutions

  • Home Purchase
  • Refinance Rates
  • Texas Cash-Out
  • VA Loans
  • Get Pre-Approved
  • Texas Loan Limits

Resources

  • Daily Rates
  • Calculators
  • HELOC Calculator
  • Loan Comparison
  • Mortgage Blog
  • STX Perks
  • Careers
  • About Us

Texas Locations

  • All Texas locations
  • San Antonio
  • Austin
  • Houston
  • Dallas
  • Fort Worth
  • Corpus Christi

Legal & Support

  • Contact Us
  • Privacy Policy
  • Terms of Service
  • State Licenses & NMLS
  • Accessibility
  • Data Opt-Out

Awards & Recognition

  • National Mortgage News Top Producers 2025
  • 5 Star Award, Top Producer
  • Five Star Professional, Rising Star
  • Top Mortgage Professionals, 2025

Memberships

  • National Association of Hispanic Real Estate Professionals (NAHREP)
  • Five Star Professional
  • Top Mortgage Professionals 2025
  • Romanian American Business Owners of America

South Texas Lending Team is a mortgage team of Neighborhood Loans, Inc. (NMLS #222982). All loans are made by Neighborhood Loans, Inc. Verify on NMLS Consumer Access.

San Antonio, TX Branch · NMLS #2774284 · 1846 N Loop 1604 W, Ste 205, San Antonio, TX 78248

Branch Manager: Benjamin Gheliuc · Mortgage Loan Originator · NMLS #1775990 · Branch line: (630) 246-4777

Corporate Headquarters: Neighborhood Loans, Inc., 1333 Butterfield Rd, Suite 600, Downers Grove, IL 60515. For complaints or questions about this branch, contact the Texas Department of Savings and Mortgage Lending, 2601 N. Lamar Blvd, Suite 201, Austin, TX 78705, 1-877-276-5550.

© 2026 Neighborhood Loans, Inc. All rights reserved.

NMLS #222982NMLS Consumer Access
Equal Housing Lender
Talk to Ben(210) 750-6164
No SSN • 60 SecSee Options
Home>Purchase>Manufactured Homes
Manufactured Home Loans

Texas manufactured home loans. Same programs. Same rates. Smarter price.

FHA, VA, USDA, and conventional mortgages for HUD-code manufactured homes. Finance your home and land together with as little as 0% down.
Check my eligibility Call (210) 750-6164
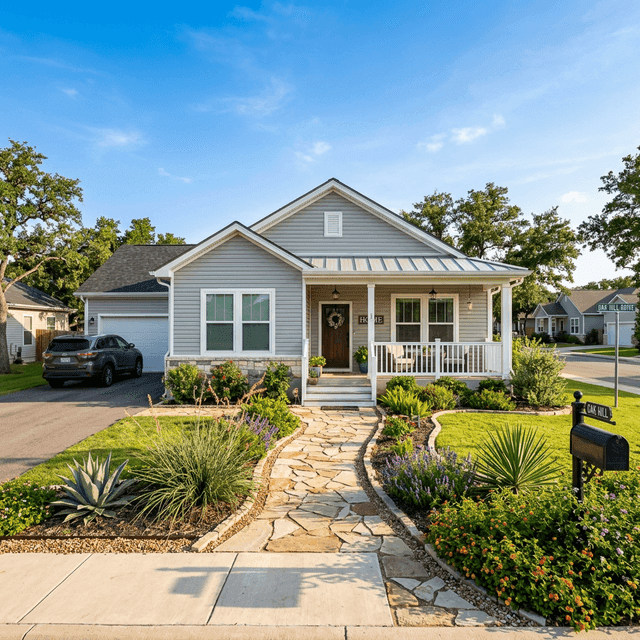
Modern manufactured home in Texas with landscaped yard
Manufactured Home
0% down VA • 3.5% FHA
0%
Down (VA/USDA)
3.5%
Down (FHA)
$832K
Max conforming

Manufactured home eligibility checklist

Your home must meet these standards to qualify for mortgage financing.

HUD-Code Required

Your manufactured home must be built after June 15, 1976 and display a HUD certification label. Pre-1976 'mobile homes' are not eligible for most mortgage programs.

Permanent Foundation

The home must be permanently affixed to a foundation that meets HUD or local code requirements. Wheels, axles, and hitches must be removed.

Titled as Real Property

The manufactured home must be titled as real property (real estate), not personal property. Texas allows conversion from personal to real property through the county.

Land Ownership

For FHA, VA, USDA, and conventional loans, you must own the land (or purchase it simultaneously). Leased-land homes require chattel financing.

Primary Residence

FHA, VA, and USDA loans require the manufactured home to be your primary residence. Conventional loans may allow second homes in some cases.

Double-Wide or Larger

Most mortgage programs require a minimum of a double-wide (multi-section) manufactured home. Some FHA programs accept single-wide with restrictions.

Why finance a manufactured home?

Manufactured homes deliver modern quality at 30–50% less than site-built — and qualify for the same mortgage programs. Compare scenarios in our mortgage calculator.

Finance home + land together

Combine the manufactured home purchase and land into a single mortgage. No separate land loan needed. Your loan covers the home, land, transportation, and installation.

Save 30–50% vs. site-built

Manufactured homes cost $55–$130 per square foot vs. $150–$250 for site-built. A 2,000 sq ft manufactured home can save you $100K–$200K compared to new construction.

Same loan programs, same rates

FHA, VA, USDA, and conventional loans for manufactured homes follow the same guidelines and offer similar rates as site-built home mortgages.

Land equity as down payment

Already own the land? Your land equity can serve as your down payment, potentially eliminating the need for cash out of pocket.
See if I qualify
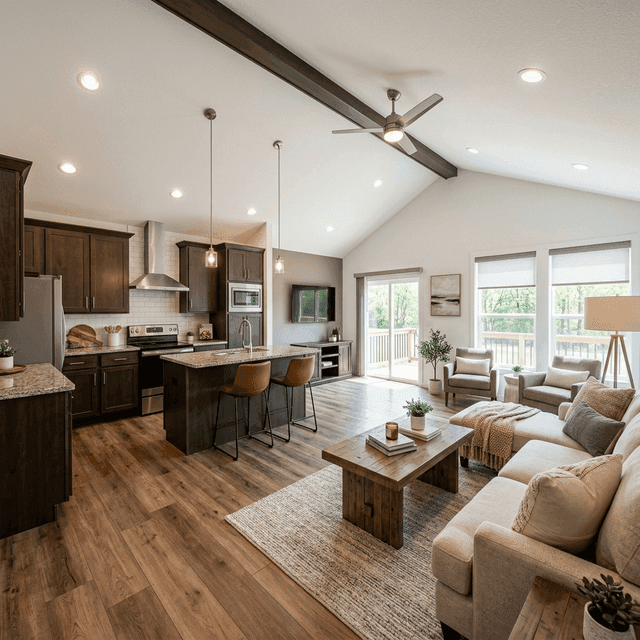
Modern manufactured home open-concept kitchen and living room in Texas

Manufactured home loan comparison

FHA vs. VA vs. Conventional vs. Chattel — side by side.

Feature
FHA
VA
Conventional
Down payment
3.5%
0%
5%
Min credit score
580
580–620
620–700
Mortgage insurance
MIP (life of loan)
VA funding fee (one-time)
PMI (cancels at 20%)
Max loan amount
$498,257 (floor)
No limit
$832,750
Land required
Yes (owned)
Yes (owned)
Yes (owned)
Home type
Single or double-wide
Double-wide (most lenders)
Double-wide
Build date
After June 15, 1976
After June 15, 1976
After June 15, 1976
Permanent foundation
Required
Required
Required
Primary residence
Yes
Yes
Not required (some)
Land equity as down
Yes
Yes
Yes
Loan term
Up to 30 years
Up to 30 years
Up to 30 years
Best for
Low credit, low down
Veterans (0% down)
Strong credit, PMI removal

Chattel loan vs. real property mortgage

Understanding the difference — and why real property wins.

Feature
Real Property Mortgage
Chattel Loan
What it finances
Home + land together
Home only (personal property)
Interest rates
Standard mortgage rates (6–7%)
Higher rates (7–12%+)
Loan term
Up to 30 years
15–20 years
Down payment
0–5%
5–20%
Appreciation
Appreciates like real estate
May depreciate
FHA/VA/USDA eligible
Yes
No (FHA Title I only)
Tax deductions
Mortgage interest deductible
Limited/none
Best for
Buyers who own or buy land
Leased-land communities

Manufactured home purchase in 4 steps

From pre-approval to move-in.

01

Get pre-approved

We assess your credit, income, and land situation to identify the best program — FHA, VA, USDA, or conventional. Pre-approval typically takes 24–48 hours.

02

Select your home & land

Choose your manufactured home from a dealer or private seller. If you don't own land, we finance the land purchase simultaneously in one loan.

03

Foundation & conversion

Your home is installed on a permanent foundation. We coordinate the real property conversion with your county so the home is titled as real estate.

04

Close & move in

One closing covers everything: home, land, foundation, and installation. Your loan converts to a standard 30-year mortgage. Welcome home.

Manufactured Home Loan FAQ

Common questions about financing manufactured and mobile homes in Texas.

Yes. FHA, VA, USDA, and conventional mortgages are all available for manufactured homes in Texas. The home must be built after June 15, 1976 (HUD code), permanently affixed to a foundation on owned land, and titled as real property. Both single-wide and double-wide homes can qualify, depending on the program.
The distinction is based on the build date. Homes built after June 15, 1976 are 'manufactured homes' and meet federal HUD construction and safety standards. Homes built before that date are 'mobile homes' and typically don't qualify for standard mortgage financing. The terms are often used interchangeably in casual conversation, but lenders make a clear distinction.
VA loans: 0% down for eligible veterans. USDA loans: 0% down in eligible rural areas. FHA loans: 3.5% down with 580 credit score. Conventional loans: 5% down with 620–700 credit score. If you already own the land, your land equity can count toward the down payment.
A chattel loan finances only the manufactured home structure as personal property — similar to a car loan. Rates are higher (7–12%+) and terms shorter (15–20 years). A real property mortgage finances the home and land together as real estate, with standard mortgage rates and 30-year terms. Converting to real property gives you access to the best financing.
Yes, VA loans are available for manufactured homes that meet HUD standards, are on a permanent foundation, on owned land, and will serve as your primary residence. VA manufactured home loans offer 0% down and no PMI. Not all VA lenders do manufactured home loans — STX Lending has specific experience in this area.
No. Both new and existing (used) manufactured homes can be financed, provided they were built after June 15, 1976, meet HUD code standards, are on a permanent foundation, and pass appraisal. FHA has specific condition requirements that the home must meet.
Yes. FHA, VA, USDA, and conventional programs allow you to combine the manufactured home purchase and land purchase into a single loan. This is the simplest approach — one closing, one loan, one payment.
Texas Senate Bill 785, effective September 1, 2026, requires municipalities to permit new HUD-code manufactured homes in at least one residential zoning classification. This expands where manufactured homes can be placed in Texas cities and may increase property values for manufactured home communities.

Ready to finance your manufactured home?

Free manufactured home consultation

Check your eligibility

Talk to a manufactured home specialist

(210) 750-6164

Quality home, smart price, Texas land

FHA • VA • USDA • Conventional — all available for manufactured homes.

Check my eligibility