STX Lending, Texas Mortgage Lender
  • Rates
(210) 750-6164Get Started
STX Lending

Texas Real Estate Lending, Simplified. We provide fast, transparent mortgage lending with competitive rates and a streamlined digital experience.

1846 N Loop 1604 W, Ste 205

San Antonio, TX 78248

(210) 750-6164hello@stxlending.com

Hours

Monday to Saturday: 7:00 AM to 8:00 PM

Sunday: Closed

Proudly serving Texas since 2019.

Find us on Google Business Profile.

Solutions

  • Home Purchase
  • Refinance Rates
  • Texas Cash-Out
  • VA Loans
  • Get Pre-Approved
  • Texas Loan Limits

Resources

  • Daily Rates
  • Calculators
  • HELOC Calculator
  • Loan Comparison
  • Mortgage Blog
  • STX Perks
  • Careers
  • About Us

Texas Locations

  • All Texas locations
  • San Antonio
  • Austin
  • Houston
  • Dallas
  • Fort Worth
  • Corpus Christi

Legal & Support

  • Contact Us
  • Privacy Policy
  • Terms of Service
  • State Licenses & NMLS
  • Accessibility
  • Data Opt-Out

Awards & Recognition

  • National Mortgage News Top Producers 2025
  • 5 Star Award, Top Producer
  • Five Star Professional, Rising Star
  • Top Mortgage Professionals, 2025

Memberships

  • National Association of Hispanic Real Estate Professionals (NAHREP)
  • Five Star Professional
  • Top Mortgage Professionals 2025
  • Romanian American Business Owners of America

South Texas Lending Team is a mortgage team of Neighborhood Loans, Inc. (NMLS #222982). All loans are made by Neighborhood Loans, Inc. Verify on NMLS Consumer Access.

San Antonio, TX Branch · NMLS #2774284 · 1846 N Loop 1604 W, Ste 205, San Antonio, TX 78248

Branch Manager: Benjamin Gheliuc · Mortgage Loan Originator · NMLS #1775990 · Branch line: (630) 246-4777

Corporate Headquarters: Neighborhood Loans, Inc., 1333 Butterfield Rd, Suite 600, Downers Grove, IL 60515. For complaints or questions about this branch, contact the Texas Department of Savings and Mortgage Lending, 2601 N. Lamar Blvd, Suite 201, Austin, TX 78705, 1-877-276-5550.

© 2026 Neighborhood Loans, Inc. All rights reserved.

NMLS #222982NMLS Consumer Access
Equal Housing Lender
Talk to Ben(210) 750-6164
No SSN • 60 SecSee Options
Home>Purchase>Renovation
Renovation Financing

Do it all together - buy, renovate and finance with one Texas loan

FHA 203(k) and HomeStyle renovation loans let you purchase a fixer-upper and finance the renovation in a single mortgage. Based on the after-repair value.
Start my renovation loan Call (210) 750-6164
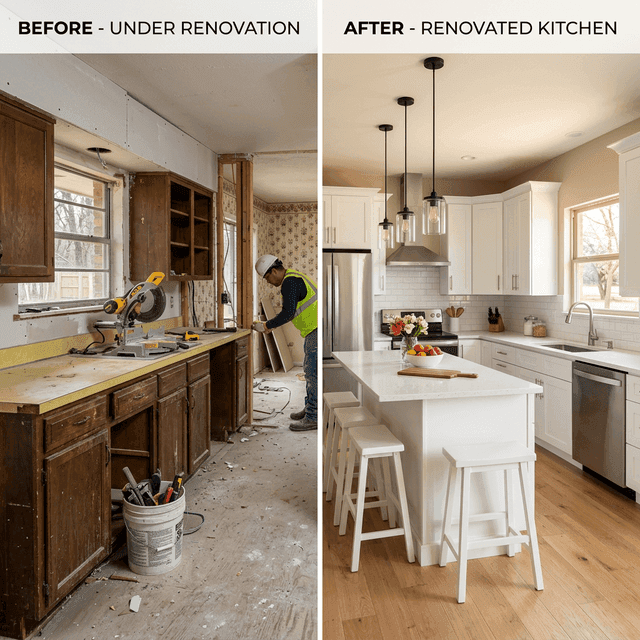
Texas home kitchen renovation before and after
Renovation Loan
Buy + renovate in 1 loan
3.5%
Min down (FHA 203k)
$35K+
Renovation funding
1 loan
Purchase + reno

Why use a renovation mortgage?

In a competitive Texas market, homes that need work (fixer uppers) often come at a better price. A renovation loan gives you the chance to turn that property into exactly what you want. Run the numbers in our mortgage calculator with the after-repair value baked in.

One loan, everything included

Instead of having multiple loans, you can combine both the purchase and renovation costs into one mortgage. There will be no need for a separate personal loan, construction loan or HELOC after.

Buy below market, renovate to value.

You can purchase a home below market value and finance the updates needed to bring it up to its full market value. This way, you build equity from day one.

Based on after-repair value

Your loan amount is based on the home's projected value after renovations — not its current as-is value. This means more purchasing power.

FHA & conventional options

FHA 203(k) loans offer low down payment options starting at 3.5%, while Fannie Mae's HomeStyle program follows conventional guidelines with fewer restrictions in certain areas. Estimate cash-to-close with our closing-costs calculator.
Get my renovation estimate
Beautifully renovated Texas home bathroom

FHA 203(k) vs. HomeStyle

Feature
FHA 203(k) Limited
FHA 203(k) Standard
HomeStyle
Down payment
3.5%
3.5%
3–5%
Min credit score
580
580
620
Max renovation $
$35,000
No limit (up to FHA max)
Up to 75% of ARV
Structural work
No
Yes
Yes
HUD consultant
No
Required
No
DIY allowed
No
No
Limited
Luxury upgrades
No
No
Yes (pool, landscaping)
Mortgage insurance
MIP (life of loan)
MIP (life of loan)
PMI (cancels at 20%)
Timeframe
6 months
6–12 months
12 months
Best for
Minor cosmetic updates
Major renovations
Flexible, higher credit

Renovation loan in 4 steps

01

Get pre-approved

We help you determine how much you qualify for, including both the purchase price and the renovation budget.

02

Find your fixer-upper

Find the right property and gather contractor estimates for the work. We will work directly with the contractor and if its an FHA Standard 203(k), a HUD consultant will be involved as well.

03

Close on your loan

You can close on the home, with renovation funds placed into an escrow account. You'll begin making your regular mortgage payments while the work is being completed.

04

Complete your renovation

The funds are released in stages as the renovation progresses and inspections are completed. Once everything is finished, you move into your updated Texas home.

Renovation Loan FAQ

Common questions about financing home renovations in Texas.

FHA 203(k): Requires as little as 3.5% down with a 580+ credit score, it includes mortgage insurance, and requires licensed contractors. A HUD consultant is needed for Standard 203(k) loans. HomeStyle: Typically 3-5% down with a 620+ score, uses PMI (which can be removed at 20% equity), allows some DIY work, doesn't require a HUD consultant, and offers more flexibility in renovation types.
Both loan programs cover major updates like kitchen and bathroom remodels, room additions, roofing, HVAC, plumbing, structural repairs, energy-efficient upgrades, and accessibility improvements. HomeStyle also allows for higher-end features like pools and landscaping. FHA 203(k) Limited is designed for smaller projects up to $35,000, while the Standard version is used for more complex structure renovations.
The funds are held in escrow and paid out in phases as the work is completed, just like it is with the construction loan. Before each draw is released to the contractor, an inspector verifies the work. Throughout the process, you continue making your normal mortgage payment.
With FHA 203(k), all work must be done by licensed contractors. HomeStyle may allow some do-it-yourself work for non-structural updates, as long as it meets guidelines and passes inspection.
The FHA 203(k) Limited you have up to 6 months. And the FHA 203(k) Standard is typically 6 to 12 months. With HomeStyle it is up to 12 months, and a possible extension to 15. All work must be completed before the escrow period ends.
Absolutely. Both FHA 203(k) and HomeStyle can be used to refinance your current mortgage while including renovation costs. This is a great option if you want to upgrade the home you already own.

Ready to renovate?

Free renovation consultation

Estimate your project

Talk to a renovation specialist

(210) 750-6164

Fixer-upper? Dream home.

One loan. Purchase + renovation. Built-in equity.

Start my renovation loan