Quick Answer: Zoning laws are put in place as local rules to divide up the city into certain districts so that we set what each property can be used for, such as homes, businesses, industrial, commercial, and/or even farming. Zoning will typically limit lot size, density, and building height, and local governments within the city or counties write and enforce these. An appraiser will report the home's zoning when you get a home loan.
How zoning laws shape what you can buy and build
Zoning is one piece of the property that most people ignore. When you walk a house and find out the garage, ADU, or separate apartment isn't legal, only then do you find out what zoning really means. I have dealt with this both on the lending side and the building side because every appraisal report says it. If you are a first-time home buyer, you need to make sure what you're looking to do with the property has the base zoning from your local jurisdiction to support the goals. If it does not then you'll need to understand what a variance is as well.
How zoning laws work
There are really two documents that we have to look at: the city's rulebook and the map you can find online. The map will drop every parcel into that designated zoning district. Together these make up the zoning ordinance, which dictates the land use for each particular parcel. For each district every parcel will show base zoning and a schedule will show what you can do for each zoning designation. The size side is what the city checks before it issues building permits for a new house or an addition:
- Minimum lot size and lot width
- Setbacks, and how far buildings sit from the front, side, and rear property boundaries
- Max height, and how much of the lot buildings can cover
- Density, or how many homes fit on a lot or an acre of land
- Parking, fence, signs, and accessory buildings like sheds and garage apartments
Between these two sides, that's most of what zoning laws determine. The purpose is to keep conflicting uses separate from each other so a manufacturing plant cannot be next door to an elementary school. The city plans roads and infrastructure around what is allowed to be built.
Zoning is only on the public layer. On top of that sit the HOA bylaws and deed restrictions, which are normally private dealings amongst property owners and can even overlay the zoning by banning things the city would also allow.
Who makes zoning laws
Your city, in most cases. There are no federal zoning laws so each state lets the cities write their own zoning regulations, which is usually under an enabling law modeled on one the Commerce Department drafted in the 1920s. The whole idea of this is a little bit newer than people might think. New York City wrote the first citywide zoning ordinance in 1916 and it took until 1926 for the Supreme Court to sign off on the fight they had in Village of Euclid v. Ambler Realty.
What does it mean? The zoning depends on what you're asking for. The City Council will adopt the code and the map after the Planning Commission sets their terms. Exceptions will go to the Board of Adjustments at the city, which everyone just calls the Zoning Board. Big changes also have to abide by the city's master plan and go through public hearings where neighbors, citizens, and anyone with a concern can show up to protest.
Types of zoning
| Zoning type | What it usually allows | Common codes |
|---|---|---|
| Residential | Houses, townhomes, or apartments, depending on the district | R-1, R-2, R-3, RM |
| Commercial | Stores, offices, restaurants, hotels | C-1, C-2, B |
| Industrial | Factories, warehouses, heavy equipment yards | I-1, I-2, M |
| Agricultural | Farming, ranching, and homes on large lots | A, AG |
| Mixed-use | Homes and businesses in the same building or block | MU, MX |
| Special districts | Planned unit developments, historic districts, overlay zones | PUD, H, O |
Treat the letters as a starting point, since every city picks its own.
Corporations or projects with bigger pockets get their own tools. A planned unit development (PUD) is approved as one package with its own zoning, lot sizes, and streets. Conditional zoning is a rezone with strings attached that come in the form of an overlay, like a building height cap or setbacks that are put in place. You'll also see floating zones, which sit in the code until the project is approved and all zoning is signed off on from both the board and city council. Normally affordable housing units and new developments have to go through this entire process. If you buy in a historic district, there could be an overlay within the base zoning that protects the area's historic character, and usually a design review process is also put in place.
What R-1, R-2 and R-3 zoning mean
Cities inside of Texas will use R1 for a single-family, meaning you can have one house on this lot and not much room for extra units. Duplexes will show up as R2, with townhomes and apartments from R3 and up. Don't assume San Antonio or Bexar County works that way (here is the San Antonio zoning schedule). The unified development code will use the number of lot size in thousands of square feet to dictate the square footage: for example, an R4 lot needs 4,000 square feet, R5 needs 5,000 square feet, and R6 needs 6,000 square feet. Whatever the letters suggest, the code's district table has the final say.
Manufactured homes will come up a lot because there are not many specifics in it. Some cities treat a manufactured home on a permanent foundation like any other house in a residential zone, and others limit mobile homes to certain districts. Be sure to check those before you buy land and plan to put one in. Our manufactured home loans page covers the financing side.
Mixed-use zoning
Think of apartments over a cafe. That's mixed-use zoning and homes and businesses sharing a building or block. Mixed-use development is like that because it puts errands within walking distance for residential units behind this mixed-use parcel. Financing gets tougher, though, when you're trying to do something commercial because it sits in front of a residentially zoned parcel and is deemed to have more strict guidelines. A condo in one of these mixed-use buildings gets an extra check since the lender's cap on how much of a condo project can be commercial is also assessed. Some investment properties with mixed-use zoning run into problems as the investors we lock with (meaning the companies that buy our loans) don't like them because the zoning has potential for higher mixed-use commercial. If you are purchasing an investment property, our DSCR loans evaluate rental income against debt service without personal tax return requirements.
Ready to start your home buying journey?
See custom rates and loan scenarios tailored to your budget in minutes. No hard credit pull, zero obligation.
How zoning affects buying and financing a home
An appraiser will report the property zoning on every mortgage and submission they give to the lender. For Fannie Mae the appraiser picks one of the four boxes:
- legal conforming
- legal non-conforming
- no zoning
- illegal
The second one is what people call grandfathered-in zoning.
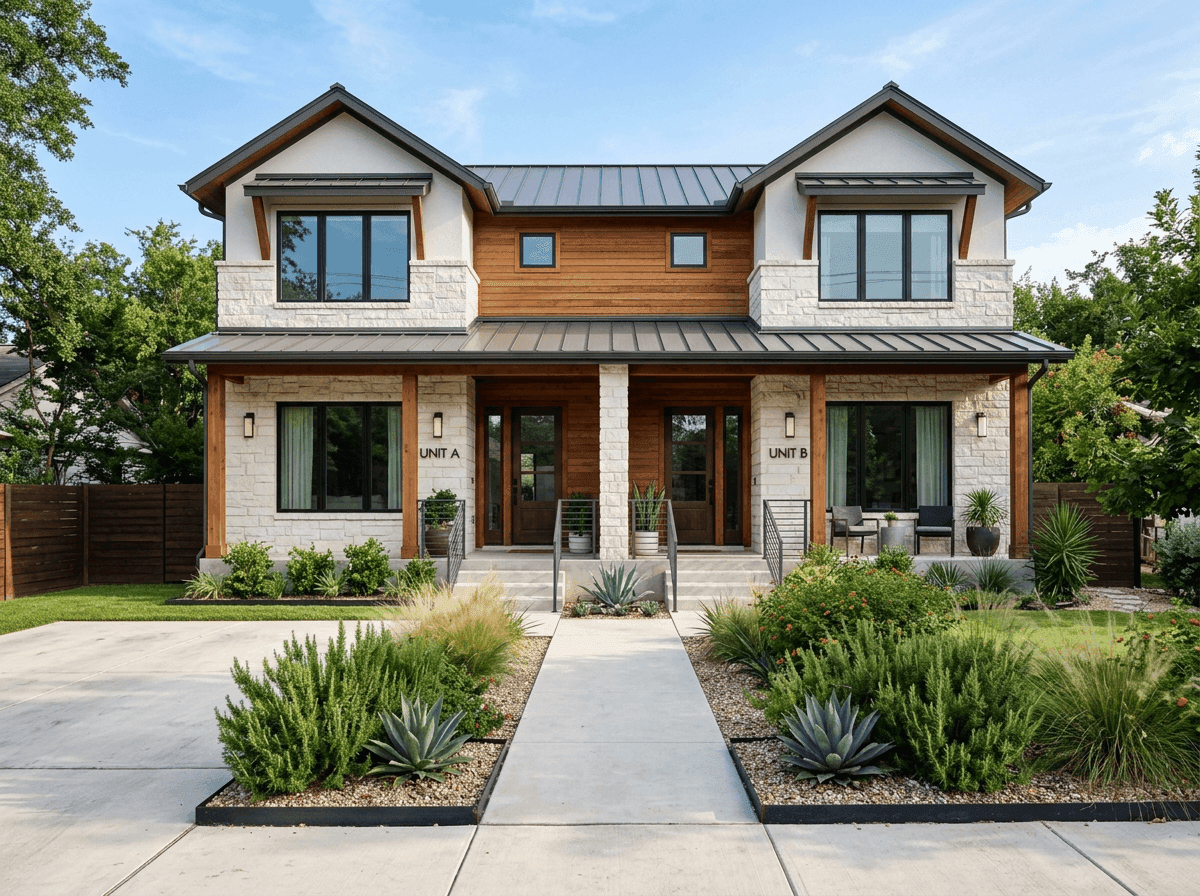
This goes for the duplex that was once legal when it was put up, on a street that's since been rezoned for single-family homes. Doesn't fit today's zoning restriction but it still gets to stay. As for a conventional loan, that can still finance it as long as the appraisal accounts for any adjustments to value. FHA loans will go even further, as the appraiser has to state whether the home can be legally rebuilt if it's destroyed. This rebuild question matters a lot for a lender. Local authorities commonly end grandfathered status once a building is more than half destroyed or deteriorated, or once the use stops for about a year.
If the box for illegal use is checked off, that is where the deal dies. Fannie Mae for conventional won't buy a loan on a property where the zoning doesn't allow for the use, with an exception for accessory dwelling units (ADUs). A garage apartment or a backyard cottage that the zoning prohibits can still be eligible when it's normal for the area. The appraiser has to find comparable homes with the same setup and ensure that there's no risk with this appraisal. FHA has no exception and its ADU has to meet the local zoning authority. If you're planning to build one, get the city's sign-off first; a renovation loan or a HELOC can fund it after that.
How to find a property's zoning
Finding the exact zoning classification for a property is straightforward when you follow these three steps:
- Search the municipal GIS interactive map: Most Texas cities maintain an interactive GIS parcel viewer, such as San Antonio's one-stop GIS zoning map. Enter the property address or parcel identification number to check the parcel's base zoning district and any special overlay districts.
- Request a zoning verification letter: If the online map is unclear or you are planning a room addition or accessory dwelling unit, contact the local municipal planning or development services department. A formal zoning verification letter spells out the parcel's zoning designation, permitted uses, and any non-conforming status recorded on file.
- Review the appraisal report (URAR): When you are under contract and your mortgage lender orders an appraisal, the appraiser completes the Site Section on Page 1 of the Uniform Residential Appraisal Report (URAR). The appraiser confirms whether the current improvements represent a legal conforming, legal non-conforming, or illegal use.
Variances, conditional use permits, and rezoning
When the zoning rules don't fit your plans, there are three ways to ask for an exception, and they aren't interchangeable:
| Request | What it changes | Example | Who decides |
|---|---|---|---|
| Variance | Relief from a physical rule on one property | A setback exception for an oddly shaped lot | Board of adjustment |
| Conditional use permit | Allows a use the district permits only with approval | A daycare or church in a residential zone | Planning commission or board |
| Rezoning | Moves the property into a different district | Residential land rezoned for shops | City council, after public hearings |
We look at the current base zoning then figure out if a variance is needed, as well as who has standing in the matter (the city, city council, zoning commission, and/or HOA). Past applications for cases similar to yours will show up in a public library so you can reference them.
Variances are very difficult to get. The board or zoning commission will grant them for a hardship that's tied to the land itself, such as an odd shape or weird slope, not because you want to build something bigger. Texas law will allow variances only when it isn't contrary to the best interests of the public and special conditions would make literal enforcement an unnecessary hardship. The board will normally need a 75% vote to grant a variance. That's also why variances often get denied, as a self-created hardship doesn't count and will not get approved.
The rezoning process is even slower, and the vote at the end is never guaranteed. Once you get the zoning commission to sign off on it, it then goes to city council and an additional public hearing. Your application will get sent out through mailed notices to all the neighbors around your property and parcel so that they have a chance to attend the hearing. Many cities also ask for a property survey with the application.
Places with no zoning: Houston and rural Texas
Houston, Texas, is a large exception. No other city in the U.S. that size has gone this long with no zoning laws and Houston voters have said no three times (once in 1948, 1962, and the third in 1993). Instead the deed restrictions and subdivision rules fill the gap, which makes HOAs and neighborhood associations important. Where no restrictions apply you get the Houston classic: a townhome next to a machine shop, next to a tattoo parlor.
Outside City Limits (OCL) is defined as no base zoning laws at all. Most Texas counties have no general power to zone when something is considered OCL, and the exceptions are narrow, so owners can largely do what they please.
OCL doesn't necessarily mean all things go, though. Deed restrictions, HOA covenants, county plats, floodplains, and septic permits all still apply. If there's a deed restriction on that property, it can sometimes be more strict than any city code, right down to the square footage of the home or the material of a roof. Read them before you choose to close on land that you plan to build on. Our lot and land loans and construction loans cover the financing side.
Zoning laws: FAQ
Typically residential, commercial, and industrial. These are the three people usually refer to, though most codes will carve out agricultural and mixed-use zoning designations.
Every borrower's situation is unique. The guidelines above are general — speak with a licensed loan officer to understand how they apply to you specifically.
Ready to Get Started?
STX Lending is a Texas-owned direct lender with decades of combined experience. Whether you're buying your first home or refinancing for better terms, our team is here to help.
Ready to start your home buying journey?
Apply online for expert-recommended options customized to your budget.
Get started